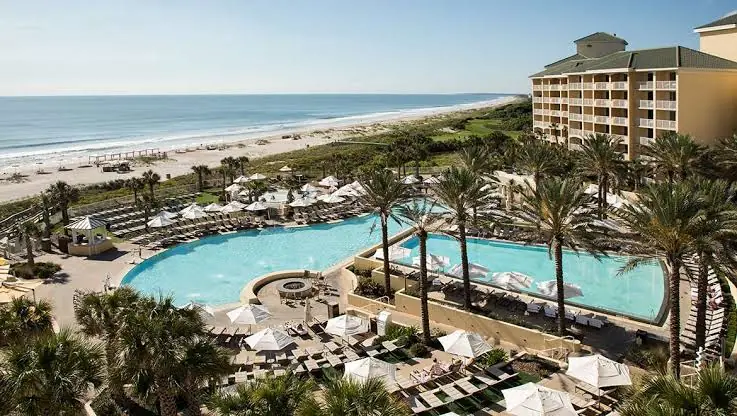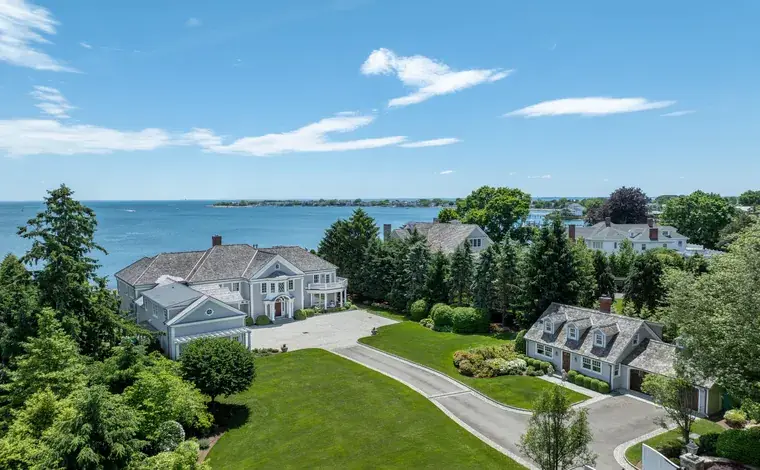
Oceanfront Living Destinations USA: Strategic Analysis and Coastal Real Estate Evaluation
Evaluating shoreline residential markets across the United States requires navigating complex physical, regulatory, and financial landscapes. The appeal of waterfront real estate is undeniable. However, properties built along the coast exist within dynamic transition zones where terrestrial systems meet marine environments. Assessing these locations requires looking past scenic appeal to examine localized coastal geology, microclimatic stressors, and evolving insurance structures.
Regional real estate markets vary significantly across American coastlines. A bluff-top property in Central California presents distinct engineering challenges compared to a barrier island residence in South Carolina. West Coast assets face seismic activity, marine layer dampness, and sea-cliff erosion. Conversely, Atlantic and Gulf Coast structures encounter tropical storm surges, severe wind loads, and active sand migration. Selecting a coastal residence demands evaluating site-specific topography alongside municipal setback mandates.
Long-term ownership of coastal real estate requires continuous capital allocation. Airborne salt spray, persistent wind pressures, and high atmospheric humidity accelerate material degradation. These environmental conditions necessitate resilient structural components and disciplined maintenance routines. Buyers who evaluate coastal properties using an integrated framework—combining geotechnical engineering, climate risk modeling, and insurance analysis—protect their capital far better than those relying solely on aesthetic appeal.
Understanding “oceanfront living destinations usa”
Multi-Disciplinary Site Evaluation
Evaluating coastal real estate requires looking beyond surface-level aesthetics. Property valuation specialists track regional inventory constraints, historical price appreciation, and localized tax structures. Structural engineers assess foundation pilings, structural wind-load resistance, and corrosion-resistant fasteners.
Environmental scientists analyze shoreline stability by evaluating sand erosion rates, natural dune formations, and localized sea-level trends. Combining these disciplines helps buyers identify structural vulnerabilities and prevent unexpected ownership costs.
Distinguishing Superficial Appeal from Structural Resilience
Expansive ocean views often mask underlying site vulnerabilities. High-end architectural finishes can conceal frame decay or improper window flashing that permits salt-air intrusion inside wall cavities.
True structural durability depends on deep piling foundations, marine-grade stainless steel hardware, and proper moisture drainage behind exterior cladding. High-performing building envelopes withstand severe weather without allowing moisture or salt aerosol penetration.
Analytical Oversimplifications
Buyers frequently evaluate coastal regions using broad geographic labels like “the West Coast” or “Florida.” These sweeping categories ignore critical microclimates, local zoning laws, and specific shoreline topography.
A home built on a protected sound bluff operates differently than a structure placed directly on an exposed oceanfront dune strand. Evaluating premier oceanfront living destinations usa requires inspecting parcel-level elevation, local setback lines, and structural storm resistance.
Deep Contextual Background
Historical Evolution of Coastal Real Estate
American shoreline development evolved from working maritime ports and seasonal fishing camps into high-value residential markets during the twentieth century. Post-war highway expansion, expanding wealth, and widespread air conditioning drove population growth toward sunbelt coastlines. Early coastal builders often ignored natural dune dynamics, erecting structures directly on unstable sands without structural piling foundations.
Regulatory Frameworks and Zoning Shifts
Severe hurricane events and rising sea levels forced structural updates to coastal building codes over recent decades. Establishing coastal setback rules, updated FEMA flood insurance rate maps, and local dune protection regulations altered development parameters.
Today, purchasing coastal property requires managing complex regulatory frameworks. Buyers must review state coastal management permits, strict impervious coverage limits, and mandatory windstorm construction standards before committing capital.
Conceptual Frameworks and Mental Models
The Coastal Exposure Triad
The Coastal Exposure Triad measures structural site resilience using three main factors: base elevation above flood lines, distance from mean high tide, and structural resistance to wind shear forces.
Deficiencies in any single factor increase overall structural risk during severe weather events. Properties built at higher elevations often withstand major coastal storms even with moderate beach setbacks.
The Life-Cycle Maintenance Escalation Model
This framework tracks how maintenance expenses accelerate near marine environments compared to inland locations. Airborne salt spray accelerates oxidation on standard steel fasteners, copper wiring, and mechanical equipment.
Understanding this cost curve helps owners budget accurately for exterior repainting, hardware updates, and mechanical unit replacements over a ten-year ownership cycle.
The Insurability Boundary Framework
This model evaluates coastal properties by their long-term insurance feasibility rather than immediate market value. Homes situated in high-risk flood zones face rising insurance premiums and reduced carrier coverage.
Structures positioned landward of state coastal construction lines remain easier to insure, preserving market liquidity during economic downturns.
Key Categories of Coastal Asset Profiles
Pacific Northwest Coastal Bluffs
Pacific Northwest coastal properties offer dramatic elevated sea-cliffs, dense evergreen forests, and cooler maritime weather. High elevations protect homes from storm surges and sea-level rise.
However, heavy seasonal rainfall and wave action along cliff bases increase long-term landslide and bluff erosion risks.
Southern California Coastal Enclaves
Southern California pairs mild year-round temperatures with strong real estate demand. High acquisition costs and low inventory characterize markets from San Diego to Santa Barbara.
Low-lying oceanfront homes face high-tide coastal erosion. Meanwhile, bluff-top properties require continuous geotechnical monitoring to track cliff retreat.
South Florida Barrier Islands
South Florida features warm ocean waters, direct beach access, and favorable state tax environments. However, low ground elevations expose properties to severe storm surges and seasonal high-tide street flooding.
Rising windstorm and flood insurance premiums represent a major recurring operating cost for barrier island homeowners.
Mid-Atlantic and New England Islands
Northern shoreline properties offer rich maritime history and sheltered harbors. These locations feature private deep-water docks, manicured grounds, and historic shingle-style architecture.
However, winter freeze-thaw cycles cause expansion cracking in masonry, while heavy seasonal nor’easters generate beach scour.
Coastal Decision Logic
Selecting a coastal region requires balancing lifestyle preferences, tax exposure, and weather risk tolerances. Buyers seeking mild temperatures often evaluate premier oceanfront living destinations usa across West Coast markets despite higher acquisition costs.
Conversely, buyers prioritizing warm waters and tax advantages in the Southeast must manage higher insurance premiums and seasonal hurricane risks.
Detailed Real-World Scenarios
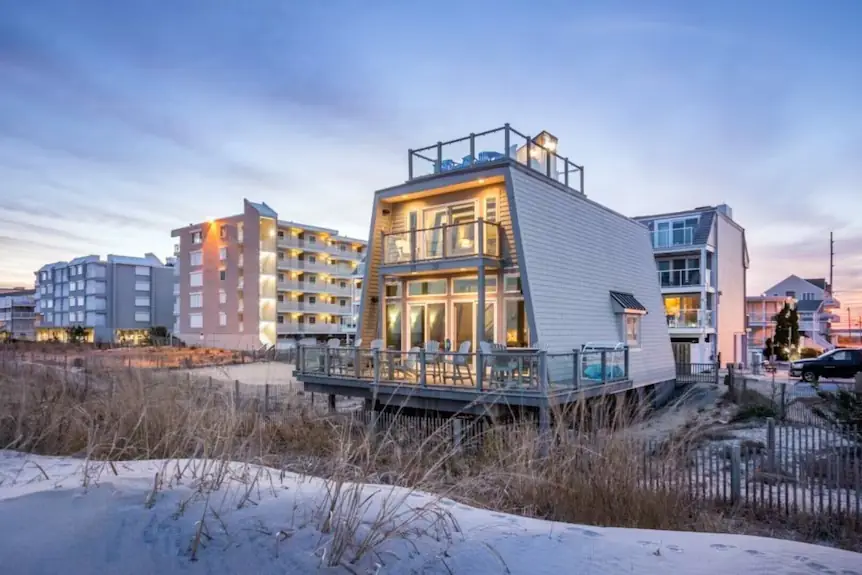
Scenario A: South Florida Low-Lying Oceanfront Residence
A buyer purchases a single-family home located directly on a South Florida barrier island. The residence features a ground-level concrete slab foundation built before modern flood elevation standards.
Systemic Stressors
-
The low foundation sits below updated base flood elevation levels.
-
Annual windstorm and flood insurance premiums increased rapidly over five years.
-
Tidal flooding periodically covers access roads, restricting vehicle travel.
Tactical Adjustments
-
Install engineered flood vents in lower walls to relieve water pressure during surges.
-
Move mechanical systems and emergency backup generators to elevated platforms above flood lines.
-
Transition structural coverage to surplus lines insurance markets to maintain policy limits.
Scenario B: Southern California Bluff-Top Estate
An investor buys a coastal property situated on a 60-foot bluff in San Diego County. Floor-to-ceiling window systems offer clear ocean views across the horizon.
Systemic Stressors
-
Bluff edge erosion washed away five feet of yard space over ten years.
-
Marine layer humidity oxidized exterior architectural steel supports.
-
Local coastal rules prohibit building new seawalls along the beach base.
Tactical Adjustments
-
Install deep concrete caissons below the ocean-facing foundation to stabilize the building.
-
Replace standard exterior hardware with 316-grade marine stainless steel fittings.
-
Construct subsurface drainage lines to direct rainwater runoff away from the bluff edge.
Scenario C: Outer Banks Barrier Island Strand Home
A homebuyer acquires an elevated timber-frame home on North Carolina’s barrier islands. The structure sits on wood pilings near an active dune line.
Systemic Stressors
-
Winter nor’easters stripped away protective frontage dunes.
-
Salt spray damaged exterior HVAC condenser coils within three years.
-
High wind events repeatedly unseated standard roof shingles.
Tactical Adjustments
-
Rebuild frontage dunes using sand fencing and indigenous beach grass planting.
-
Replace standard HVAC units with marine-coated systems featuring stainless steel hardware.
-
Re-roof using standing-seam metal panels engineered for high-wind exposure.
Scenario D: Maine Coastal Granite Bluff Property
A buyer purchases a seasonal home built atop a granite ledge overlooking Penobscot Bay. The home features exposed timber framing and fieldstone chimneys.
Systemic Stressors
-
Freeze-thaw dynamics cracked exterior stone masonry joints.
-
Heavy winter coastal winds drove rainwater behind cedar siding.
-
Steep rocky terrain complicated wastewater tank replacements.
Tactical Adjustments
-
Repoint masonry joints using flexible, low-absorption mortar compounds.
-
Install rainscreen drainage mats behind exterior wood siding to vent moisture.
-
Upgrade wastewater management to a specialized mechanical treatment unit suitable for rock terrain.
Planning, Cost, and Resource Dynamics
Operating costs for beach properties extend far beyond standard mortgage and property tax payments. Specialized maintenance schedules, utility demands, and insurance premiums raise annual ownership costs.
Labor costs for specialized coastal trades run higher than inland equivalents due to site access challenges and marine material specs. Budgeting for ongoing maintenance helps owners preserve structural integrity and prevent major repair expenses.
Tools, Strategies, and Support Systems
Site Assessment Methodologies
Evaluating oceanfront living destinations usa requires specialized analytical tools to verify long-term site viability.
-
Geotechnical Core Drilling: Core samples verify soil density, bedrock depth, and bluff stability before purchase.
-
Historical Shoreline Mapping: Reviewing decades of shoreline surveys reveals natural beach movement trends.
-
Elevation Certificates: Verifying structure heights relative to base flood lines helps predict insurance costs.
Administrative Controls
Monitoring municipal coastal management plans, tracking flood map updates, and using licensed marine contractors ensures informed property management. Maintaining thorough service records streamlines future property sales and verifies structural compliance.
Risk Landscape and Failure Modes
Understanding coastal hazards helps owners prevent compounding structural and financial issues over time.
Physical Failure Modes
-
Fastener Corrosion: Oxidized structural brackets weaken roof-to-wall framing under high winds.
-
Foundation Scour: Storm waves wash sand away from shallow footings, triggering building settlement.
-
HVAC Coil Decay: Salt air degrades copper cooling coils, leading to premature system failures.
Administrative and Financial Risks
-
Insurance Non-Renewal: Insurers exiting coastal markets can leave owners seeking high-cost surplus coverage.
-
Building Restrictions: Strict coastal regulations can limit planned home expansions or seawall additions.
-
Special Municipal Assessments: Local governments may levy special taxes to fund regional beach nourishment projects.
Governance, Maintenance, and Long-Term Adaptation
Preventive Maintenance Schedule
Regular inspections identify minor salt-air wear before it escalates into structural damage.
-
Quarterly Hardware Washdowns: Rinse exterior metal fixtures, window tracks, and door frames with fresh water to remove salt accumulation.
-
Bi-Annual Envelope Inspections: Check exterior caulking, flashing joints, and impact glass seals for water intrusion signs.
-
Annual Structural Audits: Hire a licensed engineer to inspect piling supports, deck brackets, and roof connections.
Measurement, Tracking, and Evaluation
Key Monitoring Metrics
Tracking physical and financial metrics helps owners evaluate site stability and manage annual operating budgets effectively.
Operational Documentation Examples
Maintaining clear service records documents structural quality for future buyers and insurance carriers.
Common Misconceptions and Oversimplifications
Misconception 1: “All Beachfront Real Estate Appreciates Identically”
Appreciation rates vary based on parcel elevation, beach width, and local infrastructure quality. Properties protected by wide dune systems retain value better than homes facing active shore erosion.
Misconception 2: “Seawalls Eliminate Structural Storm Risk”
Vertical seawalls reflect wave energy downward, often washing sand away from wall bases. Over time, wave action can undermine unmaintained seawalls, triggering sudden structural collapses.
Misconception 3: “Impact Windows Protect Against All Severe Weather”
While impact glass resists flying debris and wind pressurization, it cannot protect low-lying homes from floodwaters. Elevating foundations remains necessary for complete flood protection.
Ethical, Practical, and Contextual Considerations
Balancing private property enjoyment with coastal ecosystem preservation requires responsible stewardship. Installing unpermitted seawalls can accelerate erosion on neighboring lots and damage public beaches.
Public beach access laws vary by state, creating potential conflicts between private owners and visiting beachgoers. Responsible property owners evaluate premier oceanfront living destinations usa by working within local coastal management guidelines to protect their investments and surrounding natural habitats.
Conclusion
Selecting from the top oceanfront living destinations usa requires analyzing regional climate patterns, structural engineering requirements, and ongoing ownership costs. Property owners who inspect soil stability, invest in durable building materials, and plan for rising insurance costs protect their capital far better than those relying solely on ocean views.